Published 7 August 2026. Figures and market conditions described here were current at that time and may have changed since.
Many businesses are sitting on capital they do not realise they have access to. Equipment, vehicles, machinery and other assets that have been paid off or partially paid down represent value that is currently locked up in the balance sheet. Sale and leaseback is a financing strategy that allows businesses to unlock that value without giving up the use of the asset.
It is a relatively underused tool in the small to medium business space, but one that is worth understanding.
How sale and leaseback works
In a sale and leaseback arrangement, a business sells an asset it already owns to a finance company and then immediately leases it back. The business receives a lump sum of cash from the sale and continues to use the asset exactly as before, making regular lease payments to the finance company over an agreed term. At the end of the lease, depending on the structure, the business may have the option to purchase the asset back, extend the lease or return the asset.
What types of assets can be used?
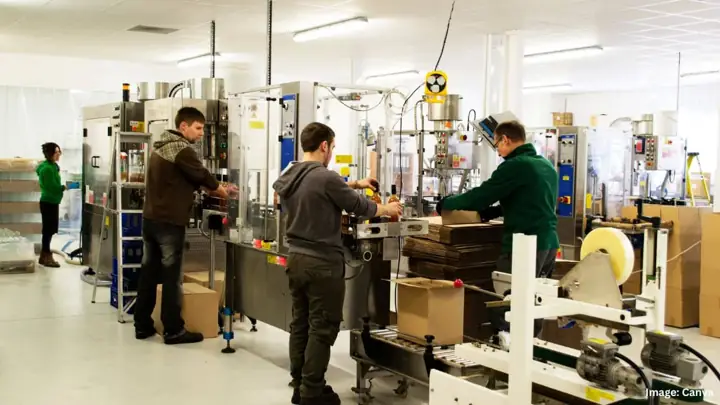
Sale and leaseback is often effective with assets that have a clear, assessable market value and a reasonable remaining useful life. Commercial vehicles, earthmoving and construction equipment, manufacturing machinery, medical and dental equipment, and technology assets are all commonly used in these arrangements. The finance company will assess the current value of the asset as part of the process, so the condition, age and marketability of the asset all influence what can be unlocked.
When it tends to make sense
Sale and leaseback is not the right solution for every situation, but there are circumstances where it is particularly well suited. A business that needs working capital but does not want to take on additional debt may find that releasing equity from existing assets is a more appropriate path than a business loan. A business investing heavily in growth that needs cash without disrupting operations can use sale and leaseback to fund expansion while keeping the assets in service. And a business that has recently paid off equipment outright may have significant value sitting idle on the balance sheet that could be put to better use.
What to consider before proceeding
There are a few considerations worth working through before entering a sale and leaseback arrangement. The ongoing lease payments become a fixed cost obligation, so understanding how they sit within your cash flow is important. The tax treatment can vary depending on how the arrangement is structured, and input from your accountant is worthwhile before committing. And as with any finance product, the terms of the lease, including the payment schedule, end-of-term options and any early exit provisions, should be clearly understood before signing.
A finance broker can help you assess whether sale and leaseback is appropriate for your situation and compare your options across lenders who offer this type of arrangement.
Want to know if this applies to you?
Talk it through with a Finfident broker. It's free and there's no obligation.